
Top reasons to sell a damaged house in New Zealand fast
TL;DR:Owning a damaged or neglected property in New Zealand often leads to rising repair costs, decreasing value, and limited buyer interest. Selling quickly as-is can save owners money, reduce stress, and avoid financing or insurance hurdles that delay or prevent sales. Honest disclosure and choosing suitable buyers, such as cash buyers, are essential to a smooth transaction.
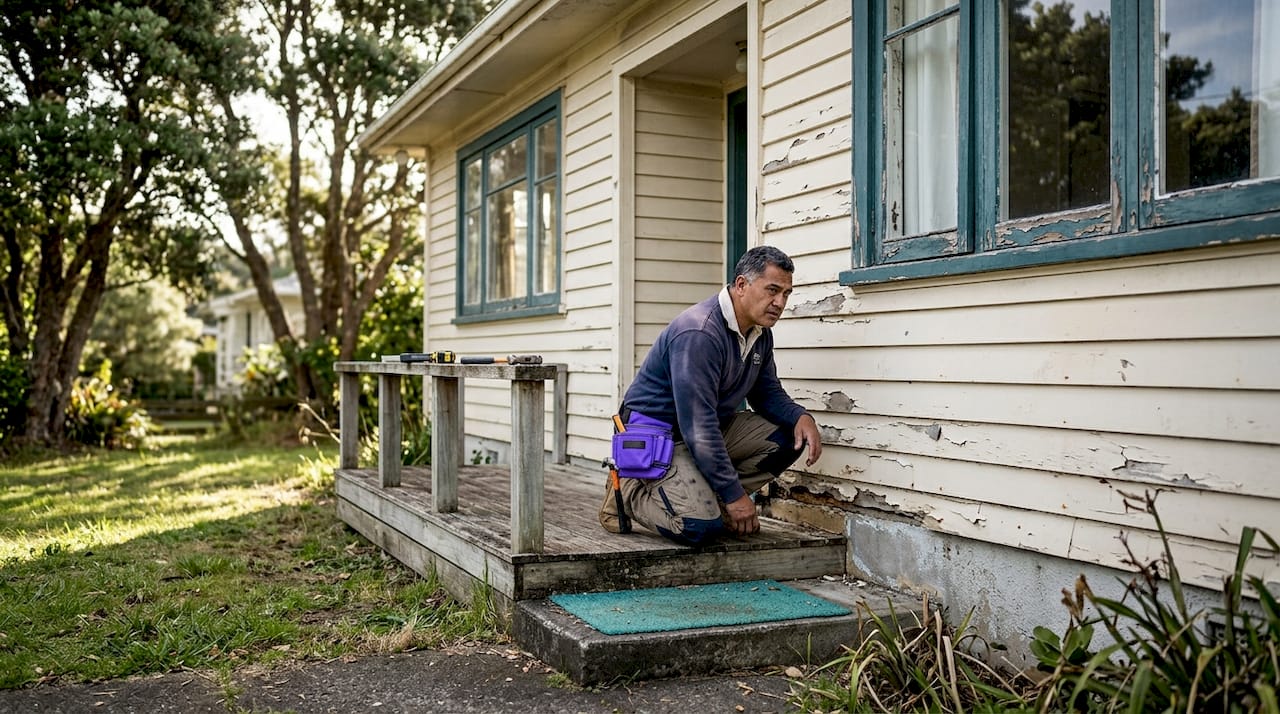
Owning a damaged or neglected property in New Zealand places you in a difficult position. Repair bills pile up, the property’s value keeps falling, and every month you delay costs you more. Mounting repair liability and reduced market value are common realities after property damage or neglect, leaving many owners weighing whether to spend more or cut losses now. This guide walks you through the key reasons why selling quickly is often the most practical decision, and how to assess which path suits your situation best.
Table of Contents
- Mounting costs and falling value
- Insurance and finance challenges
- Speed versus price: as-is versus remediation
- Disclosure obligations and legal risk
- Summary: which owners benefit most from selling?
- What most guides miss about selling damaged property
- Need help selling your damaged house?
- Frequently asked questions
Key Takeaways
| Point | Details |
|---|---|
| Repair costs mount fast | Ongoing damage leads to higher repair expenses and reduced market value. |
| Insurance and finance roadblocks | Damaged properties often can’t be insured or mortgaged easily, shrinking buyer options. |
| As-is sale is fast but lower | Selling as-is gives speed and certainty but usually fetches a lower price. |
| Disclosure required | NZ law still requires you to declare defects, even when selling a damaged house as-is. |
| Quick sales ease stress | For many, selling quickly is the best way to avoid further financial and emotional strain. |
Mounting costs and falling value
When a property suffers storm damage, structural issues, leaky building syndrome, or years of deferred maintenance, the financial pressure builds fast. Most owners underestimate just how quickly repair costs accumulate. A small roof leak left unrepaired can cause timber rot, ceiling damage, and mould growth within months, turning a $3,000 fix into a $30,000 remediation project. The longer you wait, the worse the numbers get.
Reduced market valuation and increased ongoing liability are the prime reasons owners choose to sell after significant property damage, and that pattern plays out consistently across New Zealand.
Understanding the specific ways that damage shrinks value helps you make a more informed decision. Here are the most common financial pressures owners face:
- Ongoing council rates and insurance premiums continue even if the home is uninhabitable
- Depreciation accelerates when basic maintenance is not performed, reducing the property’s condition rating used by valuers
- Buyer pool shrinks because most home loan buyers will not or cannot purchase a property in poor condition
- Negotiations skew lower as each visible defect gives buyers reason to reduce their offer further
- Holding costs compound when vacancy extends and rental income is lost
“A damaged property is not a static asset. Every week it sits without attention, its value and its appeal to buyers shrink further. Acting sooner rather than later preserves more of your equity.”
Understanding property neglect risks and how they connect to NZ properties selling below market value helps you see the full picture before you commit to one strategy.
The core financial logic is straightforward. If repairs cost $80,000 and they only add $60,000 to your sale price, you have already lost money before accounting for your time, stress, and holding costs during the renovation period. For many owners, selling now for a lower price still leaves them better off overall.
Insurance and finance challenges
Once you decide to sell, you quickly encounter another layer of complexity: not all buyers can actually purchase your property. Standard home loan lenders in New Zealand require a property to be in an insurable, liveable condition before they approve a mortgage. If your property has significant structural damage, unconsented work, or sits in a high natural hazard zone, the buyer’s bank may decline their application entirely.
Here is a step-by-step look at why the finance and insurance process breaks down for damaged homes:
- The buyer applies for a home loan and the bank orders a registered valuation.
- The valuer notes the damage or defects and flags them in the report.
- The lender conditions the loan on specific repairs being completed before settlement, or declines outright.
- The buyer approaches insurers and finds that full replacement cover is unavailable due to the property’s condition or location.
- Without insurance, the lender won’t proceed, and the sale falls over, often after weeks of negotiation.
- The seller is back to square one, having spent legal and marketing costs with nothing to show for it.
Natural hazard risk and unconsented work can make it difficult for buyers to secure full replacement insurance and satisfy mortgage lenders, which regularly motivates owners to pursue faster, simpler sales.
This cycle is exhausting and expensive. Many sellers go through it once before realising that their property simply does not suit the conventional market. The practical solution is to target buyers who do not require bank finance, such as specialist cash buyers who purchase properties in any condition.
Pro Tip: Before listing on the open market, ask your lawyer to identify any unconsented building work or outstanding code compliance issues. Knowing these upfront allows you to disclose fully and avoid a collapsed sale after weeks of effort.
If you are already wondering whether a quick sale when repairs stack up makes sense, the answer often becomes clearer once you map out the finance obstacles your buyers will face.
Speed versus price: as-is versus remediation
At this point, you face a fundamental choice: sell now in the property’s current state or invest in repairs first and aim for a higher price. Both strategies are legitimate, but they suit very different circumstances.
As-is sales allow a fast close but result in a lower sale price and fewer buyers due to perceived risk, as opposed to sales that follow full remediation. Understanding the trade-offs clearly helps you choose the right approach.
| Factor | Selling as-is | Selling after remediation |
|---|---|---|
| Sale timeline | Days to weeks | Months (repairs + marketing) |
| Upfront costs | None | $20,000 to $150,000+ |
| Buyer pool | Smaller (investors/cash buyers) | Larger (all buyers) |
| Price achieved | Below market | Closer to or at market |
| Risk level | Low for seller | Higher (cost blowouts, delays) |
| Certainty | High | Moderate |
| Stress | Low | High |
The table makes it clear that the best choice depends on your priorities. If you need certainty, speed, and minimal upfront cost, selling as-is suits you well. If you have the time, capital, and emotional bandwidth to manage a renovation, remediation may recover more value.
There are situations where remediation makes clear financial sense: cosmetic damage that costs little to fix, properties in high-demand locations where buyers compete strongly, or homes where a single identifiable repair removes all lender objections. However, for most owners dealing with serious structural issues, weather-tightness problems, or significant neglect, the cost and time involved in remediation often erodes the price premium.
Pro Tip: Get two or three quotes from licensed builders before deciding on remediation. Repair costs in New Zealand have risen significantly since 2022, and many owners are surprised to find that the estimated cost of repairs is higher than expected. Compare that figure honestly against the price difference between an as-is offer and a post-repair valuation.
Selling as-is is increasingly common in New Zealand as owners recognise the practical advantages of speed and certainty over chasing a slightly higher price through a complex and risky remediation process.
Disclosure obligations and legal risk
Even when you choose to sell as-is, New Zealand law does not allow you to stay silent about known problems. This is a point that some sellers misunderstand, believing that an as-is sale relieves them of all responsibility. It does not.
New Zealand law requires clear disclosure of known defects or unconsented work, even when selling as-is, with possible legal consequences if this obligation is ignored.
Here is what the disclosure obligation means in practice:
- You must disclose any structural issues, leaks, or damage that you are aware of
- You must declare unconsented building work, including additions, garages, or plumbing changes completed without a building consent
- You must inform buyers of any outstanding council notices, code compliance issues, or weathertightness claims
- You cannot deliberately hide information that would materially affect a buyer’s decision to purchase or the price they would pay
“Failing to disclose known defects in New Zealand can expose sellers to claims under the Consumer Guarantees Act or the Contract and Commercial Law Act, potentially leading to cancelled contracts, damages claims, or delayed settlements long after you believed the sale was complete.”
The legal risk of non-disclosure is not theoretical. Buyers who discover hidden defects after settlement can pursue remedies through the courts or the Real Estate Authority disputes process. This is the last thing you need after trying to simplify your life by selling.
Understanding the legal risk in damaged home sales is essential. The good news is that full, honest disclosure upfront is actually your best protection. Cash buyers who specialise in damaged properties factor known issues into their offer and do not come back later with surprise claims.
Summary: which owners benefit most from selling?
Not every damaged property owner is in the same position. Some have the resources to remediate and wait. Others are under genuine financial or personal pressure to act quickly. The table below summarises the most common scenarios and the selling approach that tends to work best for each.
| Seller situation | Key challenge | Best approach |
|---|---|---|
| Financially distressed | Cash flow stress, mortgage arrears | Sell as-is, fast settlement |
| Inherited damaged property | Unfamiliar with property, no capital | As-is sale, simple process |
| Facing relationship separation | Need to divide assets quickly | Fast cash offer, clean exit |
| Relocating for work | Cannot manage repairs remotely | As-is sale, flexible settlement |
| Uninsured damage (flood, fire) | No funds for repair | Sell as-is to cash buyer |
| Unconsented work issues | Finance obstacles for buyers | As-is, specialist buyer |
| Investment property with major defects | Ongoing liability, negative cash flow | Sell as-is, exit position |
Owners often sell damaged or neglected homes when faced with mounting liability, falling values, insurance red tape, or an urgent need for funds, and that covers a wide range of New Zealanders right now.
To quickly identify where you fit, consider these points:
- If you cannot afford repairs without taking on more debt, selling as-is is almost certainly your most practical option
- If buyers keep losing finance on your property, the conventional market is not working for you
- If the property is vacant and costing you monthly, every day you delay is money out of your pocket
- If you need a settlement date that suits your timeline, a cash buyer offers flexibility that auction and agency sales rarely match
Reviewing the steps for a fast sale can help you move from assessment to action without unnecessary delay.
What most guides miss about selling damaged property
Here is an uncomfortable reality that most property guides skip over: price is not always the most important variable. For many New Zealand homeowners, the real cost of holding a damaged property is not calculated in dollars alone.
The stress of managing a property that has serious problems is significant. Fielding calls from tenants, coordinating tradespeople, dealing with council inspections, and managing the anxiety of a declining asset affects your mental health and your ability to focus on other parts of your life. That cost is real, even if it does not appear on a spreadsheet.
We see this play out regularly. Owners who hold out for six to twelve months to achieve a slightly higher price often report that the experience was not worth it. The shrinking buyer pool and compounding holding risks mean that selling quickly frequently limits both financial and personal stress in ways that a higher eventual price does not fully compensate.
New Zealand’s legal and insurance environment also rewards honest, quick transactions. When you sell fast to a specialist buyer, you disclose fully, settle cleanly, and move on. There are no lingering obligations, no post-settlement disputes, and no ongoing liability for a property you no longer own.
The practical wisdom here is this: do not let the pursuit of the highest possible price become the enemy of a good outcome. A fair offer that settles in two weeks and lets you move forward with your life is often more valuable than a slightly higher offer that takes eight months, costs you in holding expenses, and carries the risk of falling over at settlement.
Exploring distressed property solutions can open up options you may not have considered, particularly if you have been focused solely on the traditional agency route.
Need help selling your damaged house?
If this article has helped you recognise that a fast, as-is sale might be the right path forward, the next step is straightforward. At easySale.co.nz, we buy damaged and distressed properties across New Zealand, offering fair cash offers with no real estate agent fees, no commissions, and no pressure.

Whether you are dealing with fire or flood damage, structural issues, unconsented work, or simply a property that needs more work than you can manage, we can help. Our process is simple: submit your property details, receive a no-obligation offer, and settle on a timeline that works for you. We also assist with fast retirement and downsizing sales when life changes demand a quick, clean outcome. For as-is NZ home sales, we are ready to make you a fair offer today.
Frequently asked questions
Can you sell a damaged house ‘as-is’ in New Zealand?
Yes, you can sell a house as-is, but as-is sales still require full legal disclosure of all known defects or unconsented works to avoid post-settlement disputes or legal claims.
What are the risks of waiting to repair before selling?
Delays increase both liability and reduce future market value, as damage typically worsens over time and repair costs can far exceed any price premium gained from waiting.
How does property damage affect getting a buyer’s finance approved?
Buyers may struggle to obtain finance or insurance if the house has major defects or sits in a hazard zone, which significantly reduces your pool of eligible purchasers.
Will I get less money if I sell my house as-is?
Generally yes, as-is sales typically attract fewer buyers and lower offers because buyers factor repair costs and unknown risks into what they are willing to pay.
Who benefits most from selling a damaged property quickly in New Zealand?
Quick sales suit owners with mounting liability, falling values, and urgent timelines, including those facing financial hardship, relationship changes, or insurance and finance obstacles on the open market.
Recommended
