
Role of Cash Buyers in NZ Home Sales
Stress from unexpected life changes or financial pressure can make selling your property in New Zealand feel overwhelming. When time is tight or a home needs repairs, traditional buyers often fall short. Cash buyers offer genuine speed and certainty, eliminating financing delays and providing rapid solutions for homeowners wanting relief. This article explains how cash buyers transform property sales, ensuring sellers achieve fast settlements and avoid the risks that come with conventional sales.
Table of Contents
- Cash Buyers In New Zealand Property Sales
- Why Cash Buyers Matter In Today’s Market
- Market Presence And Regional Impact
- How Cash Buyers Differ From Traditional Purchasers
- When Cash Buyers Become Your Best Option
- How The Cash Sale Process Works
- Understanding The Agreement For Sale And Purchase
- How Legal Conveyancing Works
- Settlement: Where The Exchange Happens
- Timeline Expectations
- Benefits For Sellers And Buyers
- Advantages For Sellers
- Advantages For Buyers
- Why Both Parties Win
- Market Benefits
- Legal Rules And Seller Safeguards
- The Legal Framework For Property Sales
- Verifying The Buyer’s Cash
- Your Responsibilities And Disclosures
- Settlement Protection
- If Problems Arise
- Risks, Pitfalls, And Best Alternatives
- Common Risks In Cash Sales
- Pitfalls To Avoid
- When Alternatives Might Be Better
- Evaluating Multiple Offers
- Building Your Decision Framework
Key Takeaways
| Point | Details |
|---|---|
| Role of Cash Buyers | Cash buyers are increasingly influential in the New Zealand property market, providing liquidity and speeding up transactions for sellers. |
| Advantages for Sellers | Selling to cash buyers leads to faster settlements, reduced stress, and fewer complications than traditional transactions. |
| Legal Protections | Legal safeguards remain intact in cash sales, ensuring all transactions comply with New Zealand law and protecting seller interests. |
| Risks and Considerations | Cash transactions can pose risks such as rushed due diligence; sellers should evaluate offers thoroughly before proceeding. |
Cash Buyers in New Zealand Property Sales
Cash buyers play a growing and increasingly important role in the New Zealand residential property market. They’re individuals or companies who purchase properties using available funds rather than relying on bank financing, and their presence shapes how properties change hands across the country.
Unlike traditional purchasers who need mortgage approval, cash buyers eliminate financing delays. This speed is transformative for sellers facing urgent circumstances. Whether dealing with property damage, financial strain, or life changes, cash buyers offer a pathway to rapid settlement without the uncertainty of loan approvals.
Why Cash Buyers Matter in Today’s Market
Cash buyers stabilise market activity across multiple regions, particularly during periods when traditional buyer activity slows. Their involvement brings genuine liquidity to the market, creating opportunities for sellers who might otherwise struggle to find buyers.
Key advantages cash buyers bring to the market include:
- No financing contingencies – Settlement doesn’t depend on mortgage approval timelines
- Quick decision-making – Offers typically come within days, not weeks
- Flexible settlement terms – Buyers can often accommodate sellers’ specific timing needs
- Property condition flexibility – Many accept properties requiring repairs or renovation
- Reduced transaction complexity – Fewer moving parts means smoother sales processes
Cash buyers fundamentally change the sales equation by removing the two biggest delays traditional buyers face: mortgage processing and inspection-based renegotiations.
Market Presence and Regional Impact
Across New Zealand, cash buying activity has increased notably, with these buyers taking advantage of market fluctuations and growing property listings. They’re particularly active in regions experiencing slower traditional sales activity, where their presence can spark renewed momentum.
Cash buyers aren’t limited to distressed properties either. They operate across all segments, from entry-level homes to premium properties, adapting their strategies to different market conditions and seller circumstances.
How Cash Buyers Differ from Traditional Purchasers
When you sell to a cash buyer, you’re entering a transaction fundamentally different from a standard real estate agent sale. The buyer has capital ready to deploy immediately, meaning no waiting for mortgage pre-approval letters or bank valuations.
Sellers working with cash buyers typically experience:
Here’s how cash buyers and traditional buyers stack up in New Zealand property transactions:
| Aspect | Cash Buyers | Traditional Buyers |
|---|---|---|
| Transaction speed | Typically 2–4 weeks | Usually 6–12 weeks |
| Settlement certainty | Very high—funds ready | Lower—finance approval needed |
| Inspection flexibility | Often accepts ‘as-is’ | Inspections and renegotiations |
| Negotiation leverage | Strong due to speed | Depends on financing process |
| Market impact | Increases liquidity, stability | Slows in subdued conditions |
- Faster initial offers (usually 3–5 days)
- Simplified negotiations without lender requirements
- Fewer inspection contingencies or renegotiations
- Ability to close on the seller’s preferred timeline
- Greater certainty that the deal will proceed to settlement
When Cash Buyers Become Your Best Option
Certain situations make cash buyers the optimal choice. If you’re facing financial pressure, property damage, or life transitions, cash buyers understand your urgency and work with realistic timeframes. They’re also ideal if your property requires significant repairs that would deter traditional lenders or if you need to settle quickly.
Many homeowners also prefer cash buyers simply to avoid the stress of traditional sales—no open homes, no extended negotiations, no uncertainty about whether financing will fall through.
Pro tip: When contacting cash buyers, be transparent about your timeline and property condition—this allows them to provide accurate offers quickly without wasting time on properties that don’t fit their criteria.
How the Cash Sale Process Works
The cash sale process in New Zealand follows clear, straightforward steps that differ significantly from traditional financed purchases. Since the buyer doesn’t need mortgage approval, the entire transaction moves faster and with fewer complications.
When you accept a cash offer, you’re entering a legally binding agreement that typically settles much quicker than conventional sales. The buyer has funds ready to deploy, meaning no delays waiting for bank valuations or loan approvals.
Understanding the Agreement for Sale and Purchase
Once you accept an offer, both parties sign standardised property sale documentation governed by the REINZ/ADLS Agreement. This contract outlines the property details, sale price, settlement date, and conditions.
With cash buyers, the agreement typically contains fewer contingencies than traditional sales:
- No financing condition – The buyer doesn’t need loan approval
- Simplified inspections – Many cash buyers accept properties as-is or with limited inspection periods
- Flexible settlement dates – You and the buyer agree on timing that suits both parties
- Clear payment terms – Funds are held in trust until settlement
How Legal Conveyancing Works
You’ll appoint a solicitor or conveyancer to manage the legal aspects of your sale. This person verifies the buyer’s cash is legitimate, checks your property title, and ensures everything complies with New Zealand law.
Your legal representative will:
- Conduct title searches through official property procedures to identify any encumbrances
- Prepare all necessary contracts and settlement documents
- Manage communications between both solicitors
- Hold settlement funds in a trust account
- Register the title transfer with Land Information New Zealand (LINZ)
This layer of legal protection ensures you’re protected and the cash buyer’s funds are genuine.
Settlement: Where the Exchange Happens
Settlement is the final stage where ownership transfers and you receive your money. Your solicitor coordinates with the buyer’s solicitor to arrange the exact date and time.
On settlement day:
- The buyer’s solicitor transfers funds to your solicitor’s trust account
- Your solicitor confirms receipt and availability of funds
- Both parties’ solicitors coordinate the title transfer
- LINZ records the new owner in the official property register
- You receive your sale proceeds (minus legal fees and adjustments)
The entire settlement process happens within hours once both solicitors confirm funds are cleared and all documents are signed.
Timeline Expectations
A cash sale typically progresses like this:
- Days 1–2: You accept offer and appoint your solicitor
- Days 3–7: Conveyancing work (title checks, contract preparation)
- Day 8: Both parties sign the Agreement for Sale and Purchase
- Days 9–14: Settlement funds held in trust; final preparations
- Days 15–21: Settlement occurs and title transfers
The entire process from accepted offer to completed sale usually takes 2–4 weeks. This is significantly faster than traditional sales, which often take 6–12 weeks.
Pro tip: Appoint your solicitor within 24 hours of accepting an offer—the faster your legal representative starts due diligence, the quicker settlement can occur.
Benefits for Sellers and Buyers
Cash sales create a win-win scenario for both parties involved. Sellers gain speed and certainty, whilst buyers secure properties without financing complications. Understanding these mutual benefits helps explain why cash transactions are increasingly popular across New Zealand.
When you sell to a cash buyer, you’re accessing a streamlined process that traditional sales simply cannot match. The advantages flow in both directions, making cash sales attractive during uncertain economic periods.
Advantages for Sellers
Selling to a cash buyer addresses the biggest pain points homeowners face. You eliminate waiting periods, reduce stress, and gain genuine certainty that your sale will proceed.
Key seller benefits include:
- Faster settlement – Complete sales in 2–4 weeks instead of 6–12 weeks
- No financing contingencies – The buyer doesn’t need loan approval, so your sale won’t collapse due to mortgage issues
- Fewer inspections and renegotiations – Many cash buyers accept properties as-is, avoiding costly requests for repairs
- Reduced stress – No open homes, no lengthy negotiations, no uncertainty
- Certainty of completion – Once agreed, the deal proceeds to settlement without risk of falling through
Cash buyers provide faster completion especially during subdued market conditions, which is valuable when you’re facing financial pressure or life changes.
Advantages for Buyers
Cash buyers gain significant leverage and flexibility in their acquisitions. They can move quickly on opportunities and negotiate from a position of strength.
Buyer benefits include:
- Negotiation power – Offering certainty and speed often secures better property deals
- No mortgage delays – Access funds immediately without bank processing timelines
- Reduced transaction complexity – Fewer contingencies and simpler paperwork
- Flexible settlement – Can negotiate settlement timing to suit their business requirements
- Asset diversification – Direct property ownership without leverage or ongoing debt servicing
Why Both Parties Win
Cash transactions streamline the entire sales process by removing traditional friction points. Avoiding mortgage conditions and delays allows both parties to achieve smoother ownership transfers without the complications that plague conventional sales.
The removal of financing contingencies is transformative. Sellers get certainty; buyers get speed. Neither party needs to worry about loan approvals falling through at the last moment.
Cash sales eliminate the two biggest risks in property transactions: financing falling through and inspection-based renegotiations that drag out the process.
Market Benefits
Cash buyers contribute significantly to market health by providing liquidity during uncertain periods. When traditional buyers are cautious, cash buyers step in and transact, keeping properties moving and supporting broader market activity.
This activity benefits everyone:
- Sellers gain access to motivated buyers when traditional demand is weak
- Buyers acquire properties with less competition and faster negotiations
- Markets remain active and stable, supporting broader economic confidence
- Property prices stabilise through consistent transaction volume
You’re not just making a transaction—you’re participating in a more efficient market.
Pro tip: When evaluating a cash offer, focus on the certainty it provides rather than just comparing price to agent estimates—a guaranteed sale is worth more than a potentially higher price that falls through.
Legal Rules and Seller Safeguards
Selling to a cash buyer doesn’t mean bypassing legal protections. New Zealand law requires strict compliance with property sale regulations, and these safeguards exist specifically to protect your interests. Understanding your legal rights ensures you’re protected throughout the transaction.
Every property sale in New Zealand, regardless of whether the buyer is paying cash or financing, must follow established legal frameworks. Your solicitor or conveyancer plays a crucial role in enforcing these protections.
The Legal Framework for Property Sales
Property law guidelines establish comprehensive standards that govern all transactions, including sales to cash buyers. The REINZ/ADLS Agreement for Sale and Purchase is the standard contract used across New Zealand, ensuring consistent legal protections for sellers and buyers.
Your key legal protections include:
- Standardised contract terms – The REINZ/ADLS Agreement protects your interests with balanced clauses
- Conveyancer oversight – Your solicitor verifies the buyer’s capacity to pay and checks all documentation
- Title verification – Your legal representative confirms ownership and identifies any encumbrances or restrictions
- Trust account holding – Settlement funds are held in a solicitor’s trust account, not released until conditions are met
- Settlement safeguards – LINZ registration ensures you receive payment before ownership transfers
Verifying the Buyer’s Cash
Before accepting a cash offer, your solicitor will verify the buyer’s genuine financial capacity. This isn’t about distrust—it’s standard practice that protects you from fraudulent buyers.
Verification includes:
- Proof of funds (bank statements or financial institution letters)
- Confirmation the funds are legally obtained
- Verification the funds are available for immediate settlement
- Checks for any liens or claims against the money
Your solicitor won’t release settlement documents until funds are confirmed as genuine and available.
Your Responsibilities and Disclosures
You have legal obligations when selling property. Sellers must comply with disclosure requirements regarding property condition, known defects, and any legal issues affecting the property.
You must disclose:
- Structural defects or damage you’re aware of
- Previous flooding or water damage
- Pest infestations
- Building consent or code compliance issues
- Body corporate disputes (for apartments)
- Boundary disputes or access issues
Failing to disclose known issues can result in legal action after the sale, so transparency is essential.
Settlement Protection
Settlement is where your legal protections culminate. Both parties’ solicitors ensure all conditions are met before the final exchange occurs.
On settlement day:
- Your solicitor confirms receipt of funds in their trust account
- Title transfer documents are prepared and ready
- LINZ registration is submitted simultaneously with payment
- You receive your sale proceeds
- The buyer receives registered title
Settlement happens simultaneously—you don’t hand over the property until funds clear, and the buyer doesn’t pay until title transfers.
If Problems Arise
Property law provides remedies if issues emerge. If a cash buyer fails to settle after signing the Agreement, your solicitor can pursue legal action to enforce the contract or seek damages.
Common protections include:
- Contract enforcement through the courts
- Penalty clauses for non-performance
- Interest charges on delayed settlements
- Recovery of your legal costs
This is why having a qualified conveyancer is non-negotiable—they protect your interests through every stage.
Pro tip: Ask your solicitor for a detailed explanation of the Agreement before signing—understanding your protections upfront prevents surprises and ensures you know exactly what happens at each stage.
Risks, Pitfalls, and Best Alternatives
Whilst cash sales offer significant advantages, they’re not without risks. Understanding potential pitfalls and knowing when alternative approaches might work better helps you make informed decisions. Not every situation calls for a cash sale, and recognising this is crucial.
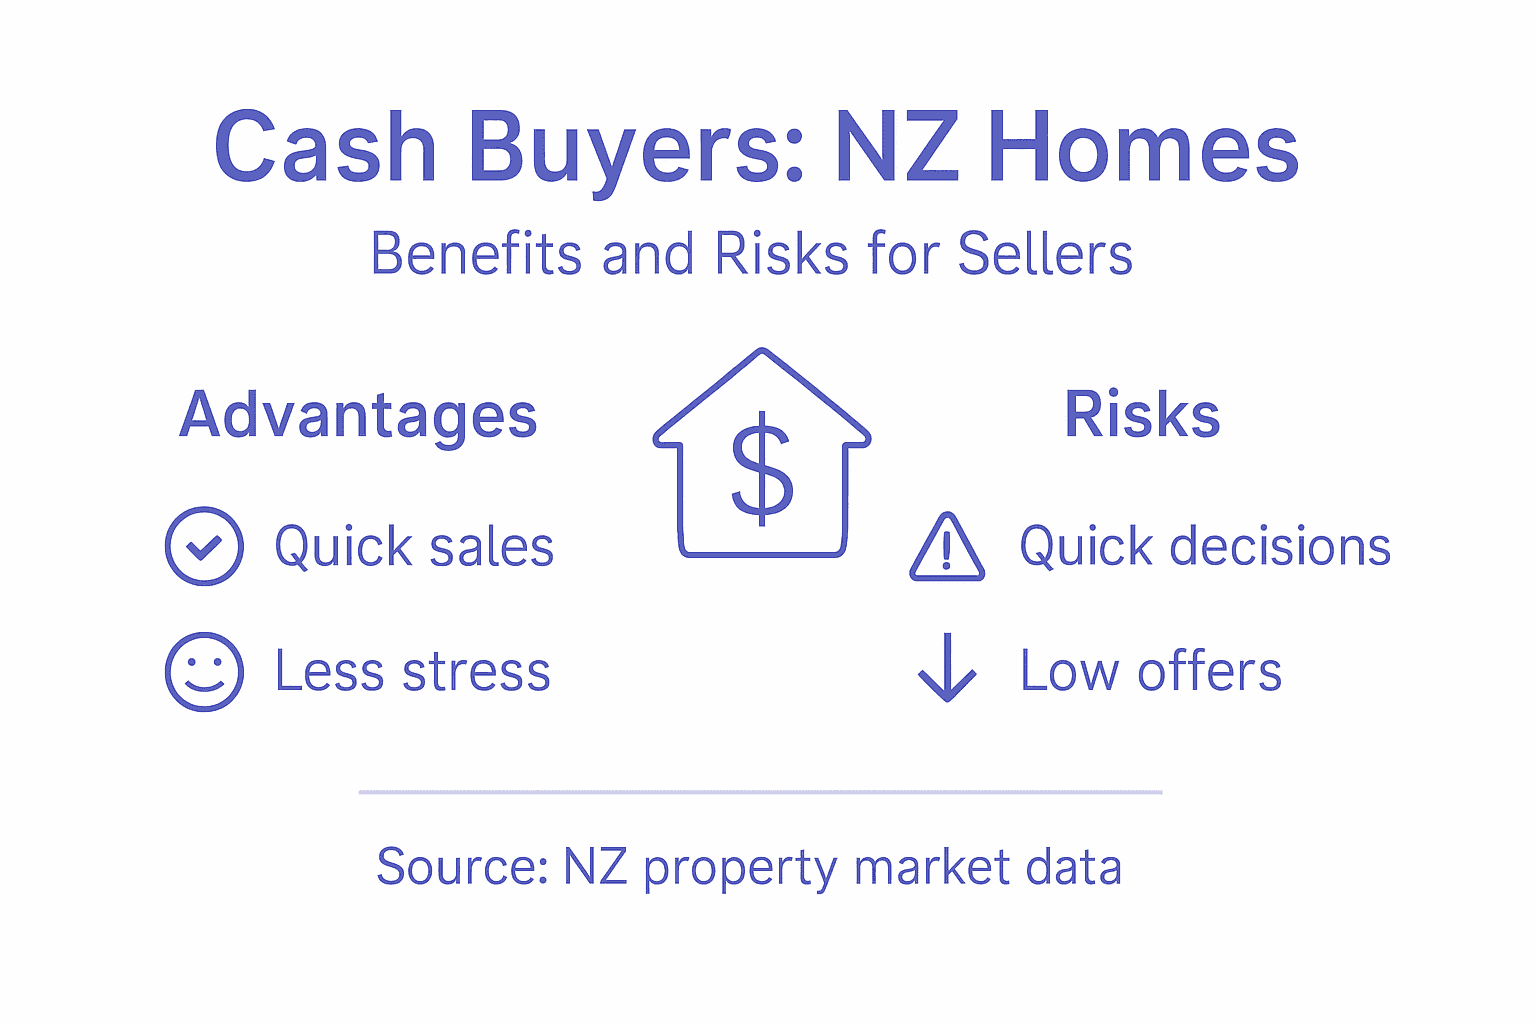
Cash transactions move quickly, which creates both opportunities and dangers. Speed can mask incomplete due diligence, leaving you exposed to problems that thorough investigation would have revealed.
Common Risks in Cash Sales
The speed of cash sales can work against you if proper safeguards aren’t in place. Market volatility and buyer capacity risks exist regardless of payment type, but accelerated timelines compound these issues.
Key risks to watch for:
- Rushed due diligence – Quick settlements can mean skipped inspections or incomplete title checks
- Fraud exposure – Cursory verification of buyer funds leaves you vulnerable to scams
- No time for reflection – Fast contracts mean less opportunity to negotiate terms that protect you
- Incomplete documentation – Speed sometimes means paperwork isn’t as thorough as it should be
- Limited property assessment – Cash buyers accepting properties as-is may not conduct full inspections
Pitfalls to Avoid
Incomplete due diligence in rapid transactions is the primary pitfall. Even though you want a fast sale, never skip verification steps your solicitor recommends.
Common pitfalls include:
- Accepting offers without verified funds confirmation
- Signing contracts before your solicitor completes title searches
- Agreeing to settlement dates that don’t allow proper preparation
- Failing to disclose known property issues to avoid delays
- Bypassing standard legal procedures to speed up the process
These shortcuts save days but cost thousands later.
When Alternatives Might Be Better
Cash sales aren’t always your best option. Conditional offers with finance clauses or staged settlements can balance speed with protection in certain situations.
Consider alternatives if:
- Your property has structural issues requiring inspection
- You need time to address building consent problems
- The cash offer is significantly below market value
- You want traditional agent marketing to attract more buyers
- You need staged settlement to arrange your next purchase
If your situation allows time, exploring multiple buyer types gives you genuine choice.
Evaluating Multiple Offers
Receiving multiple offers—including cash and financed—lets you weigh speed against price and certainty. A slightly lower cash offer with guaranteed settlement might outweigh a higher offer requiring financing.
When comparing offers, consider:
For sellers, here are key considerations when evaluating cash vs financed offers:
| Factor | Cash Offer Considerations | Financed Offer Considerations |
|---|---|---|
| Sale price | May be slightly lower | Often competitive or higher |
| Settlement risk | Minimal—less likely to fall through | Moderate—risk of failed financing |
| Stress level | Lower—less uncertainty | Higher—more negotiation steps |
| Preparation time | Short—quick due diligence | Longer—multiple document reviews |
- Net proceeds after all costs and adjustments
- Certainty of completion (not just purchase price)
- Your actual timeline needs versus advertised timelines
- Property condition requirements and inspection terms
- Settlement timing flexibility
A lower guaranteed cash offer is often worth more than a higher offer that falls through due to financing or inspections.
Building Your Decision Framework
Your financial situation, property condition, and timeline determine whether a cash sale truly serves you. If you’re facing pressure, it’s easy to accept the first offer. But pausing to evaluate alternatives protects your interests.
Ask yourself:
- How urgent is my actual need to sell?
- Is the offer fair for my property’s condition?
- What are my total costs including legal fees?
- Could waiting for more buyers improve my outcome?
- What happens if this deal falls through?
Honest answers guide you towards the right choice.
Pro tip: Before accepting any offer, get a comparative market analysis from a licensed agent to understand fair value for your property—this ensures you’re not accepting an artificially low cash offer simply because it’s quick.
Discover the Ease of Selling to Cash Buyers with EasySale.co.nz
If you are facing financial pressure, property damage, or need to sell your home quickly due to life changes a cash buyer could be your best option. The article explains how cash buyers remove the uncertainty of mortgage approvals and lengthy negotiations. EasySale.co.nz specialises in helping homeowners in New Zealand achieve a fast, fair cash sale without agent fees or commissions. Their simple process accepts homes in any condition and respects your need for a swift and stress-free sale.

Take control of your property sale today by submitting your details and receiving a no-obligation cash offer. Benefit from flexible settlement timelines tailored to your needs and avoid the headaches of traditional sales. Get started now at EasySale.co.nz and experience how cash buyers provide certainty and speed when you need it most.
Frequently Asked Questions
What are cash buyers in home sales?
Cash buyers are individuals or companies who purchase properties outright using available funds, eliminating the need for bank financing.
How do cash buyers benefit sellers?
Cash buyers provide benefits such as quicker settlement times, fewer contingencies related to financing, and the ability to accept properties in need of repairs, making the sale process smoother and less stressful for sellers.
What is the typical timeline for a cash sale?
The timeline for a cash sale typically ranges from 2 to 4 weeks from the accepted offer to settlement, significantly faster than traditional sales, which can take 6 to 12 weeks.
What legal protections exist when selling to a cash buyer?
Legal protections include standardised contracts, solicitor oversight for verifying funds, title verification, and holding settlement funds in a trust account until all conditions are met.
Recommended
