
Why accept a fast cash offer? Benefits for NZ homeowners
TL;DR:Fast cash offers provide quick, certain sales without financing delays, ideal for urgent or strategic reasons.They typically sell below market value to account for speed, condition, and buyer risk, but save on fees and time.Homeowners should compare multiple offers, review contracts carefully, and seek legal advice to avoid potential pitfalls.
Many New Zealand homeowners assume that fast cash offers are only for people in serious trouble. That assumption is costing some sellers time, money, and peace of mind. The reality is that a cash sale can be a smart, strategic choice for a wide range of situations, from urgent financial pressures to straightforward life changes like relocating or settling an estate. This guide breaks down exactly what fast cash offers are, who they suit best, and how to approach them with confidence. You’ll find real data, honest comparisons, and practical advice to help you decide whether this path makes sense for your property.
Table of Contents
- What is a fast cash offer and how does it work?
- Who should consider accepting a fast cash offer?
- How do fast cash offers compare to other selling methods?
- What should you watch out for with fast cash offers?
- The truth most homeowners miss about fast cash offers
- How we help with hassle-free, fast NZ property sales
- Frequently asked questions
Key Takeaways
| Point | Details |
|---|---|
| Speed and certainty | Fast cash offers provide a quick, guaranteed sale—often within days or weeks. |
| Ideal in urgent situations | This option suits homeowners facing financial hardship, property damage, or sudden life changes. |
| Trade-off on price | You may get a lower price than market value, but avoid agent fees and long waits. |
| Essential due diligence | Always compare multiple offers and seek legal advice to ensure a fair outcome. |
What is a fast cash offer and how does it work?
A fast cash offer is when a buyer purchases your property outright without needing a bank loan or mortgage approval. There are no finance conditions to satisfy, no waiting on a lender’s valuation, and no risk of the deal falling through because a bank said no. The buyer has the funds ready, and that changes everything about the timeline.
For New Zealand homeowners, the NZ fast offer process typically follows a straightforward path:
- Submit your property details. You provide basic information about your home, its condition, and your preferred timeframe. No need to renovate or stage the property first.
- Receive a no-obligation offer. The buyer assesses your property, often without a formal inspection, and presents a written cash offer. You are under no pressure to accept.
- Negotiate and agree on terms. Unlike a traditional sale, there is usually room to discuss the settlement date so it fits your schedule.
- Complete the legal process. A solicitor handles the transfer of title. Settlement can happen in days rather than months.
- Receive your funds. Once settlement is complete, the cash is in your account.
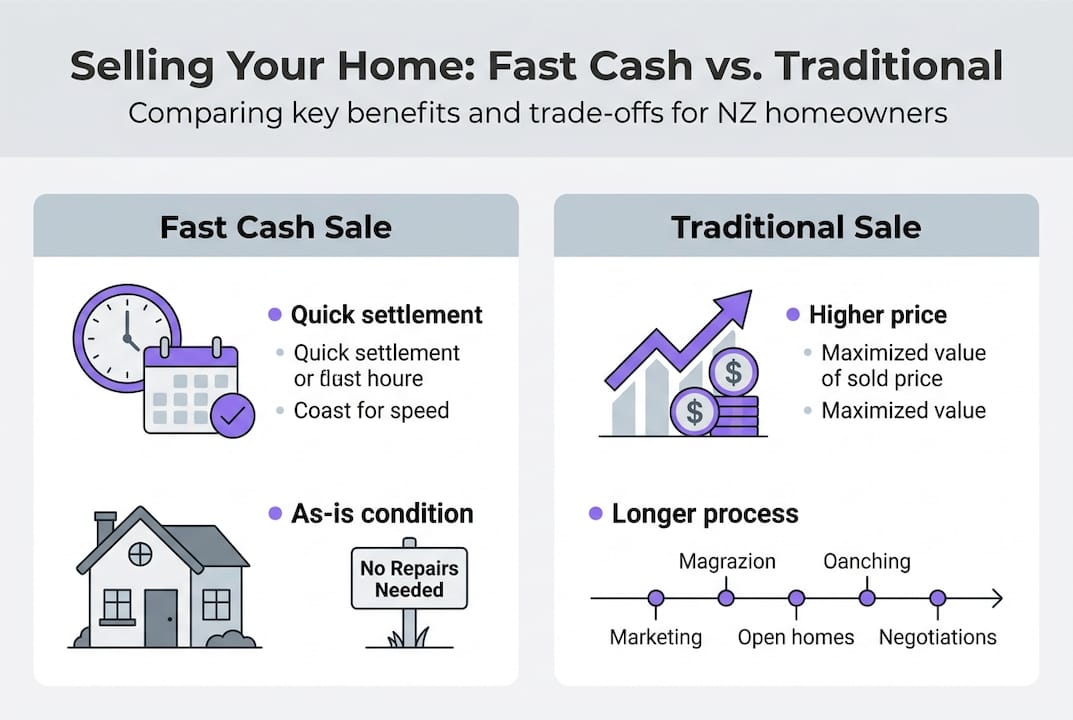
The biggest difference from a traditional sale is certainty. In a standard real estate transaction, buyers can pull out, finance can fall through, and the process can drag on for months. Cash offers enable sales in days to weeks, up to 60% faster than traditional sales with mortgage approvals. That speed is not just convenient. For many sellers, it is genuinely life-changing.
Another key feature is the as-is condition clause. Cash buyers purchase your property in its current state. You do not need to fix the leaking roof, repaint the walls, or replace the carpet. That saves you both money and stress before the sale.
Pro Tip: Always ask any cash buyer for proof of funds before signing anything. A legitimate buyer will provide this without hesitation. Also review the step-by-step cash sale guide to understand your rights and obligations throughout the process.
Who should consider accepting a fast cash offer?
Fast cash offers are not exclusively for people facing crisis. However, certain situations make them particularly well suited to this approach. Understanding where you fit can help you make a clearer decision.
Over 35% of NZ properties are sold under time pressure from financial setbacks or life changes, and cash offers provide quick liquidity when it matters most. That is a significant portion of the market, and it reflects just how common urgent sale situations are across the country.
“Over 35% of NZ properties sold under time pressure from financial setbacks or changes; cash offers provide quick liquidity.”
Here are the most common situations where a fast cash offer makes strong practical sense:
- Financial hardship. If you are behind on mortgage payments or facing repossession, a fast sale can help you clear debt and protect your credit record.
- Property damage. Homes affected by floods, earthquakes, or neglect can be difficult to sell through traditional channels. Cash buyers accept damaged homes including those impacted by events like the Christchurch earthquakes, without requiring costly repairs first.
- Urgent relocation. A new job in another city or country, a family emergency, or a change in circumstances can make a fast sale essential.
- Divorce or separation. Selling quickly can help both parties move forward without prolonged legal and financial entanglement.
- Inherited properties. Managing an estate is stressful. A cash sale can resolve the property quickly and distribute proceeds to beneficiaries without delay.
Pro Tip: Even if you are not in a desperate situation, speed has real value. Avoiding months of open homes, negotiations, and uncertainty has a genuine quality-of-life benefit that does not show up in the sale price but absolutely shows up in your stress levels. Explore the reasons for fast sale in NZ to see how others in similar positions have approached their decisions.
How do fast cash offers compare to other selling methods?
To make a genuinely informed decision, you need to see how a cash sale stacks up against the alternatives. Here is a clear comparison across the three main options available to New Zealand homeowners.
| Factor | Fast cash offer | Auction | Traditional agent sale |
|---|---|---|---|
| Timeframe | Days to weeks | 4 to 6 weeks | 2 to 6 months |
| Price achieved | Below market value | Market or above | Market value |
| Certainty | Very high | Moderate | Lower |
| Agent fees | None | Yes | Yes (2 to 4%) |
| Marketing costs | None | Yes | Yes |
| Condition required | As-is | Presentable | Good condition |
| Finance risk | None | Low | High |
The table tells a clear story. A traditional agent sale may achieve the highest price, but it comes with the most variables. Auctions can deliver strong results in a competitive market, but they are not guaranteed and require preparation. A cash offer trades price for certainty and speed.
It is worth noting that no agent commissions or marketing fees apply with cash sales, which means sellers keep more of the net proceeds than the headline price difference might suggest.
Hidden costs in traditional sales that sellers often underestimate include:
- Agent commission (typically 2 to 4% of the sale price)
- Marketing and photography packages
- Home staging costs
- Ongoing mortgage payments during the listing period
- Maintenance and presentation costs while the property is on the market
When you factor in those costs, the gap between a cash offer and a traditional sale narrows considerably. Review your property sale options NZ carefully before assuming one method is automatically better than another.
What should you watch out for with fast cash offers?
Fast cash offers have real advantages, but they are not without trade-offs. Going in with clear eyes will help you avoid the most common mistakes.
The most important thing to understand is pricing. Offers are typically below full market value to account for speed, the as-is condition, and the buyer’s repair and resale margin, often calculated as ARV (after repair value) minus repairs minus profit. That is not dishonest. It is simply how the model works. The buyer is taking on risk and providing a service, and the price reflects that.
Here is how to protect yourself and make a smart decision:
- Get at least two or three offers. Never accept the first offer without comparison. Different cash buyers will assess your property differently, and prices can vary.
- Know your property’s approximate market value. Get a free appraisal from a local agent or check recent comparable sales in your area before entering negotiations.
- Read every clause in the contract. Some buyers include terms that can delay settlement or reduce the final price. Understand what you are signing.
- Engage a solicitor. Independent legal advice is not optional. A property lawyer will identify any unusual terms and protect your interests.
- Check the buyer’s credentials. Look for reviews, testimonials, and a verifiable track record. Understand the role of cash buyers in the NZ market before committing.
Know when to walk away. If an offer feels significantly below what you expected and the buyer cannot explain their valuation clearly, that is a red flag. Legitimate buyers are transparent about how they calculate their offers. Review the guidance on how to avoid pitfalls in cash sales to stay informed.
Pro Tip: If a cash buyer pressures you to sign quickly without allowing time for legal review, walk away. Reputable buyers understand that sellers need time to make an informed decision.
The truth most homeowners miss about fast cash offers
Here is something we see repeatedly: homeowners who choose a cash sale are not always in trouble. Many are simply people who have done the maths and decided that certainty is worth more than chasing the last dollar.
There is a stigma attached to selling for cash, as if it signals failure or desperation. That framing is outdated and frankly unhelpful. We have worked with retirees who wanted a clean exit without the drama of open homes. We have seen landlords offload investment properties quickly to redirect capital elsewhere. We have helped families resolve inherited properties without months of dispute and delay.
The conventional wisdom says always hold out for market value. But market value assumes a perfect buyer, perfect timing, and a smooth process. Real life rarely delivers all three at once. Sometimes the certainty of a settled sale today is genuinely worth more than the possibility of a higher price in three months. Navigating cash sale decisions is about understanding your own priorities, not following a rule someone else wrote for a different situation.
Speed and peace of mind are legitimate financial values. Do not let anyone tell you otherwise.
How we help with hassle-free, fast NZ property sales
At easySale.co.nz, we connect New Zealand homeowners with direct cash buyers who are ready to move quickly and fairly. There are no agents involved, no commissions to pay, and no obligation to accept any offer we present.

Whether you are facing financial pressure, dealing with a damaged property, or simply want to sell on your own timeline, we can help you explore your options without the usual stress. Our process is straightforward: submit your details, receive a fair cash offer, and settle when it suits you. If you are considering a retirement or downsizing sale or prefer a private cash sale NZ, we have tailored solutions for both. Reach out today for a no-obligation conversation about your property.
Frequently asked questions
Will I get less money with a fast cash offer than a traditional sale?
Generally yes, as cash offers are below market value to account for speed, as-is condition, and buyer risk, but sellers save on agent fees and avoid costly delays that erode net proceeds.
How quickly can I sell my house with a cash buyer in New Zealand?
Sales can settle in days to weeks, which is up to 60% faster than traditional routes involving mortgage approvals and extended marketing periods.
Who is eligible to sell their property for cash in NZ?
Any homeowner can consider a cash sale, but it is most suitable for those needing a quick, certain outcome due to urgent financial or life changes such as repossession risk, divorce, relocation, or inherited property.
Are there risks to accepting a fast cash offer?
Yes, risks include lowball offers and selling below market value, so always compare multiple offers and seek independent legal advice to protect your interests before signing anything.
Recommended
