
Sell Fast in NZ: Find and Vet Cash Buyers Without a Real Estate Agent
The fastest way to sell without a real estate agent is to go straight to verified direct cash buyers or a dedicated cash-buyer platform like easySale, rather than waiting on the open market. Before you accept anything, confirm the buyer’s proof of funds and get a property lawyer involved early. Gather your title, LIM, and photos now, then either submit your details to a direct buyer or ring a lawyer to start the paperwork.
TL;DR:Verified cash buyers and platforms like easySale respond within days, but require proof of funds, legal checks, and prepared documentation to ensure safety.Speedy cash sales typically settle in 7 to 21 days with discounts of 10 to 30 percent below market value, especially for urgent situations or damaged property.Conduct thorough vetting by requesting proof of funds, legal entity verification, and settlement timelines, and always involve your lawyer before signing any agreement.Selling privately involves understanding tax implications like the bright-line test, which can result in taxable gains if property is sold within a certain ownership period.Following a structured process with legal advice and verified offers ensures a fast, fair transaction, reducing common mistakes and legal risks.
Table of Contents
- How to find buyers real estate agent free: fast channels to try today
- How do you vet a cash buyer quickly and safely?
- What’s the typical timeline and discount for a cash sale?
- Legal essentials for Kiwi sellers going it alone
- Step-by-step checklist for selling fast to a cash buyer
- Tax implications and capital gains when selling privately
- Author Aaron’s perspective: real seller mistakes and how to avoid them
- How easySale helps you sell fast without the guesswork
- Sources
How to find buyers real estate agent free: fast channels to try today
Skipping the agent doesn’t mean skipping structure. It means choosing channels that put your property in front of buyers who can move quickly, rather than ones built for a six-week marketing campaign.
Here’s where to send your details first:
- Direct-buyer forms and cash-buyer platforms — these typically ask for your address, condition, and rough timeline, and respond within a day or two with an indicative offer.
- Trade Me private listing — you skip agent fees and still reach cash-ready buyers browsing outside agency listings, though response speed depends on how well you price it.
- Local networks — lawyers, accountants, and community groups often know investors actively looking to buy, and a warm introduction tends to filter out time-wasters faster than a cold listing.
- National property-buying services — companies like easySale advertise set settlement windows and buy properties in almost any condition, which suits sellers under real time pressure.
Before contacting anyone, have your property photos, title details, and a rough price expectation ready. Buyers who ask serious questions will want this upfront, and having it prepared speeds up every conversation that follows.
How do you vet a cash buyer quickly and safely?
Speed doesn’t mean skipping checks. A legitimate buyer expects you to verify them, and a genuine one will provide proof of funds and coordinate with your solicitor rather than pushing you to sign on the spot.
Work through this order:
- Ask for proof of funds. A bank confirmation letter or a solicitor’s escrow confirmation is standard. If a buyer can’t produce either within a day, that’s a signal to slow down.
- Check the legal entity. Request photo ID for individuals, or company registration details if you’re dealing with a business. A quick search on the Companies Office register confirms the entity actually exists.
- Request references or evidence of recent purchases. A buyer with a track record will usually share this without hesitation.
- Get a written settlement timeline. Vague promises about “moving fast” aren’t good enough. You want dates.
- Never sign without independent legal advice, and insist deposits sit in a lawyer’s trust account rather than being paid directly to the buyer.
Watch for pressure to sign immediately, vague contract terms, or requests to hand over money outside a trust account. These are the classic markers of a buyer who doesn’t want scrutiny.
Pro Tip: If a buyer resists involving your lawyer at any stage, treat that as a dealbreaker. Legitimate direct buyers coordinate with your solicitor as a matter of course, not as an inconvenience.
What’s the typical timeline and discount for a cash sale?
Genuine cash buyers usually respond with an offer in 24 to 48 hours, and settlement can happen anywhere from 7 to 21 days after that, compared with months on the open market.
That speed comes at a price. Cash offers typically land 10 to 30% below market value, because the buyer is absorbing the risk of an as-is purchase, often without a building report or finance conditions slowing things down. Selling privately can also cut your costs significantly. Marketing and legal fees for a private sale often run under $5,000, against a typical agent commission of 3 to 4% of the sale price.
The discount makes sense for some sellers and not others:
- Mortgagee pressure — when a bank deadline is looming, certainty beats a higher price you might not get in time.
- Inherited property — especially when several family members want a clean, fast resolution.
- Damaged or unconsented homes — properties that would struggle on the open market anyway.
You can still negotiate terms even in a fast sale. Ask for a shorter inspection window, a staged payment structure, or a settlement date that suits your own moving plans rather than accepting the buyer’s first proposal.
Legal essentials for Kiwi sellers going it alone
Selling without an agent shifts more of the legal workload onto you and your lawyer, and skipping steps here is where private sales go wrong.
You’re legally required to disclose known defects, including weather-tightness issues and unconsented work. Settled is clear that failing to disclose known problems can lead to court action or the sale being cancelled outright, so get this right from the start.
Before you sign anything, engage a property lawyer or conveyancer. Government guidance on selling a house recommends this as standard practice, not an optional extra, because your lawyer prepares or reviews the sale and purchase agreement and holds the deposit in trust.
Check these items in any agreement before signing:
- Deposit handling and which trust account it sits in
- Conditions attached to the sale (finance, building report, LIM)
- Settlement date and what happens if either party defaults
- Whether a LIM and title search have been completed
If you own a unit-title property, extra rules apply. The Law Society notes that unit-title sales need a formal pre-contract disclosure statement, and missing it can give the buyer grounds to cancel the contract after you thought the deal was done. Always confirm your lawyer has this covered before you agree to a settlement date.
Step-by-step checklist for selling fast to a cash buyer
Once you know the channels and the legal basics, the actual process is short. Here’s the order that keeps you protected at every stage:
- Prepare your documents and photos. Locate your title and order a LIM if you don’t already have one.
- Submit your details to one or more vetted direct buyers. Ask for written offers that include proof of funds, not a verbal figure over the phone.
- Select the strongest offer and instruct your solicitor to draft or review the sale and purchase agreement, confirming exactly how the deposit will be held.
- Agree a settlement date and let your lawyer complete title, LIM, and any unit-title disclosures required for your property type.
- Finalise settlement, confirm handover logistics, and keep copies of every written offer and communication in case a dispute arises later.
Following this order rarely takes longer than a couple of weeks from first contact to settlement, assuming your paperwork is ready and your buyer is genuine.
Tax implications and capital gains when selling privately
Selling without an agent doesn’t change your tax position. What matters is how long you’ve owned the property and why you bought it, not who found the buyer.
New Zealand doesn’t have a general capital gains tax, but the bright-line test can still apply to residential property sold within a set ownership period, depending on when you purchased it and whether it was your main home. If the bright-line test applies to your sale, any gain is treated as taxable income for that year, which can be a shock if you haven’t budgeted for it.
Investment or rental properties carry different considerations again, particularly around depreciation recovered on chattels or improvements. If you inherited the property, the timing of transfer and any prior use also affects your position.
None of this is something to guess your way through. A property-savvy accountant can confirm whether the bright-line test applies to your specific sale, and it’s worth having that conversation before you accept an offer, not after settlement when your options have narrowed. Get this sorted alongside your legal review, not as an afterthought once the cash has landed.
Author Aaron’s perspective: real seller mistakes and how to avoid them
The sellers who come through a fast sale without regrets are almost always the ones who slowed down for the two things that matter: verifying funds and getting a lawyer involved before signing anything. It sounds obvious, and it’s still the step people skip when a buyer’s timeline feels urgent.
The regrets I hear about most aren’t from selling too fast. They’re from signing too fast, or assuming unit-title disclosure didn’t apply to them because “it’s just a small sale.” It always applies.
A cash sale can absolutely be fair and quick. It just needs the basic checks done in order, not skipped because someone’s in a hurry.
— Aaron
How easySale helps you sell fast without the guesswork
Easysale is the direct alternative to listing with an agent when speed and certainty matter more than squeezing out the last dollar. There’s no commission, no open homes, and no waiting on finance-conditional buyers who might fall through weeks later.

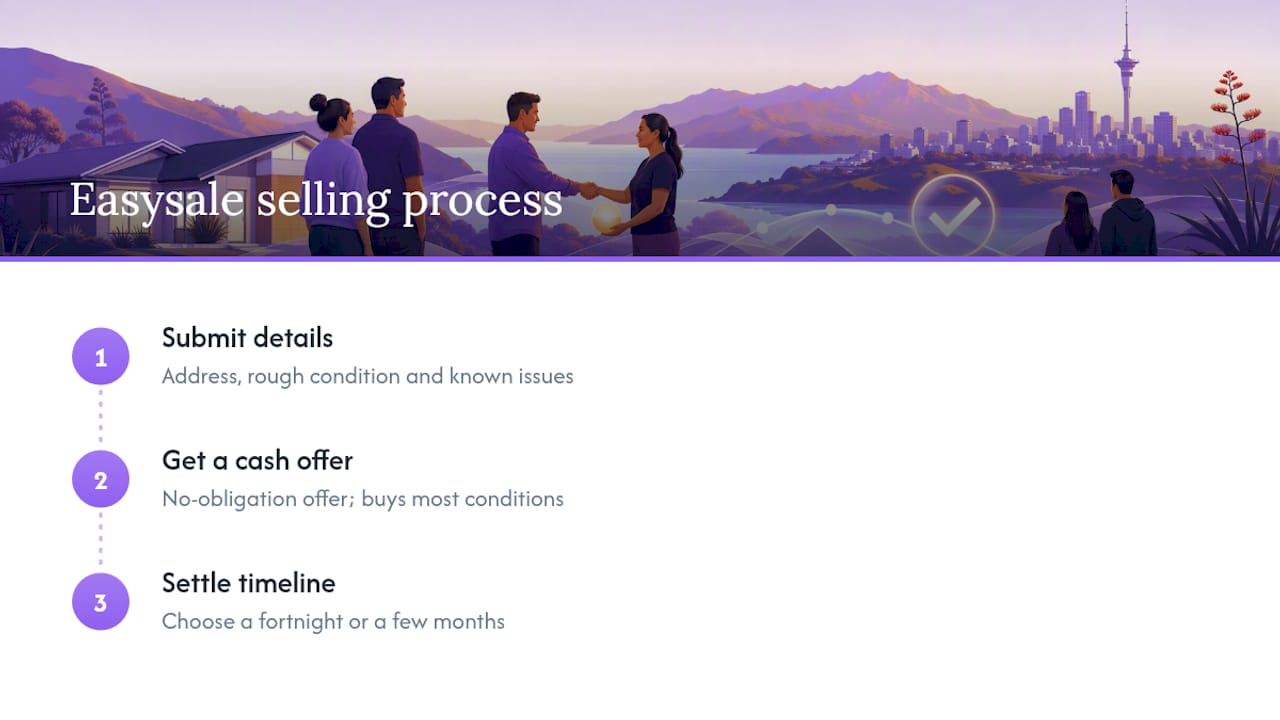
The process runs in three steps: submit your property details, receive a no-obligation cash offer, and settle on a timeline that suits you, whether that’s a fortnight or a few months out. Easysale buys homes in almost any condition, including damaged, unconsented, or tenanted properties that would struggle to attract finance-approved buyers on the open market.
Before you reach out, have your address, a rough description of the property’s condition, and any known issues ready. That’s what lets Easysale return a fair offer quickly. And whatever offer you receive, from Easysale or anyone else, get independent legal advice and verify the buyer’s proof of funds before you sign. If you’re ready to see what a fair cash offer looks like for your situation, that’s the place to start.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
Recommended
