
Selling inherited property checklist: your 2026 NZ guide
TL;DR:Selling inherited property in New Zealand requires obtaining probate, verifying ownership through the title, and managing debts and taxes carefully. Proper planning and clear communication with beneficiaries and professionals help avoid delays and legal risks during the sale process.
Selling inherited property is defined as the legal process of transferring and selling real estate that passes to you through a deceased person’s estate. For New Zealanders, this process follows a structured checklist that covers probate, title verification with Land Information New Zealand (LINZ), tax considerations under Inland Revenue rules, and coordination with beneficiaries. Getting each step right protects you from personal liability and keeps the sale on track. This guide walks you through every stage, from confirming legal ownership to settling with a buyer, so you can move forward with confidence.
1. Confirm the type of ownership on the title
The Record of Title is the first document you need. It tells you who owns the property and how. Ordering the title early prevents costly missteps that can delay the entire sale.
New Zealand properties are held in one of three main ways:
- Sole ownership: The property was in the deceased’s name alone. Probate is required before you can sell.
- Tenancy in common: Each owner holds a defined share. The deceased’s share passes through their estate and requires probate.
- Joint tenancy: Ownership passes automatically to the surviving owner. No probate is needed, but you must still update the title with LINZ.
Pro Tip: Request a current Record of Title from LINZ before taking any other steps. It confirms ownership type, flags any mortgages, and reveals caveats that could block a sale.
2. Apply for probate or letters of administration
Probate is mandatory when the deceased held real property solely in their name, or when estate assets exceed $40,000. Without it, you cannot legally transfer or sell the property.
If the deceased left a valid will, the executor applies for probate. If there is no will, a family member applies for letters of administration. The court filing fee is $269, and a compliant application typically processes within 1–2 weeks. However, the full probate process takes 4–12 weeks, and letters of administration can take 2–4 weeks for intestate estates. Third-party probate preparation services start around $699 plus GST.
| Application type | Who applies | Typical timeframe |
|---|---|---|
| Probate (with will) | Named executor | 4–12 weeks |
| Letters of administration (no will) | Family member | 2–4 weeks |
| Court filing fee | Payable on lodgement | $269 |
Pro Tip: Apply for multiple certified copies of the probate grant at the same time. LINZ requires certified copies to process title transfers, and having extras on hand avoids delays.
3. Verify and update the title with LINZ
Once probate is granted, certified copies of probate must be lodged with Land Information New Zealand to complete the title transfer. Your solicitor handles this step, but you need to supply the documents promptly.
LINZ updates the title to reflect the estate or the new owner’s name. This is a non-negotiable step before any sale can settle. Without a clean title, no buyer’s solicitor will allow their client to proceed to settlement.
4. Open an estate bank account
An estate bank account keeps the deceased’s finances separate from your own. All income from the property, such as rent, and all outgoings, such as rates, insurance, and maintenance costs, should flow through this account.
This separation protects you as executor. It creates a clear paper trail that beneficiaries can review and that satisfies any court or Inland Revenue scrutiny. Open the account as soon as you receive the death certificate and your appointment as executor is confirmed.
5. Settle outstanding debts before distributing proceeds
The estate must pay all debts before any money goes to beneficiaries. Outstanding debts include:
- Mortgage balances on the property
- Rates and body corporate fees
- Funeral and estate administration expenses
- Legal and conveyancing fees
- Court filing fees and valuation costs
Executors who distribute assets before all debts and claims are settled risk personal liability. The Family Protection Act gives eligible claimants up to 12 months from the date of the probate grant to file a claim. Waiting the full 12 months before final distribution is the safest approach.
6. Understand the tax position on the inherited property
New Zealand’s bright-line tax rules do not apply when property is inherited. Rollover relief means the transfer from the deceased’s estate to the beneficiary does not trigger an immediate tax liability. The successor is treated as having purchased the property at the same price and on the same date as the original owner.
This matters when you later sell. The bright-line period and cost base carry over from the original owner. Speak to a tax adviser or accountant before settlement to understand your specific position, particularly if the property was used as a rental.
7. Get a professional property valuation
A registered valuation gives you an accurate market value for the property. This figure serves three purposes: it informs the sale price, it satisfies Inland Revenue requirements for estate accounting, and it gives beneficiaries confidence that the property is not being undersold.
Do not rely on online estimates or council valuations alone. A registered valuer inspects the property in person and produces a report that stands up to scrutiny. The cost is typically a few hundred dollars and is recoverable from the estate.
8. Prepare the property for sale
A well-presented property attracts more buyers and stronger offers. Focus on the basics before listing:
- Clear out personal belongings and furniture, or arrange a deceased estate clearance service
- Clean the property thoroughly, including windows, carpets, and outdoor areas
- Complete minor repairs such as leaking taps, broken locks, and cracked tiles
- Tidy the garden and improve street appeal with fresh mulch or a lawn mow
- Address any obvious maintenance issues that could put buyers off or affect a building inspection
Weigh up the cost of renovation against the likely increase in sale price. For most inherited properties, a clean, tidy presentation outperforms a full renovation on return.
Pro Tip: Buyers of deceased estates often expect some wear and tear. Transparency about the property’s condition builds trust and reduces the risk of conditional offers falling over.
9. Choose a real estate agent with deceased estate experience
Agents experienced in deceased estates understand probate timelines, beneficiary dynamics, and the legal compliance requirements that standard sales do not involve. Choosing the wrong agent adds stress and can create delays that cost the estate money.
Ask prospective agents directly how many deceased estate sales they have handled in the past two years. Request references from executors, not just vendors. A specialist agent will also know how to communicate sensitively with multiple beneficiaries who may have different expectations about price and timing.
10. List the property and manage conditional agreements
You can list the property and enter a conditional sale agreement before probate is granted. Settlement requires the probate grant to proceed, but marketing during the waiting period can accelerate the final sale. Some buyers accept longer settlement periods while probate is pending.
The sale and purchase agreement should include a condition that settlement is subject to the grant of probate. Your solicitor drafts this clause. Be upfront with buyers about the expected timeline so they can plan their own arrangements.
- Engage a solicitor to draft the sale and purchase agreement
- Include a probate condition clause if probate is not yet granted
- Agree on a settlement date that allows sufficient time for probate to be issued
- Notify all beneficiaries of the proposed sale price and terms before signing
- Lodge the transfer of title with LINZ once probate is confirmed and settlement is ready
Pro Tip: Keep beneficiaries informed at every stage. Disputes between beneficiaries are the most common cause of delayed or collapsed estate sales.
11. Complete settlement and distribute proceeds
Settlement is the final step. Your solicitor coordinates with the buyer’s solicitor to transfer funds and lodge the title change with LINZ. Once settlement is confirmed, the net proceeds go into the estate bank account.
From there, the executor pays any remaining debts and costs, then distributes the balance to beneficiaries according to the will or the rules of intestacy. Keep records of every payment. A final estate account showing all income, expenses, and distributions protects you from future disputes.
Key takeaways
Selling an inherited property in New Zealand requires probate, a clean title, careful debt management, and clear communication with beneficiaries at every stage.
| Point | Details |
|---|---|
| Probate comes first | You cannot sell or transfer sole-ownership property without a probate grant from the court. |
| Title verification is non-negotiable | Order the Record of Title early to confirm ownership type and identify any encumbrances. |
| Tax rollover relief applies | Bright-line rules do not trigger on inheritance, but the original cost base and period carry over to the beneficiary. |
| Wait 12 months before distributing | The Family Protection Act gives claimants up to 12 months to file, so early distribution risks executor liability. |
| Specialist agents reduce delays | Agents experienced in deceased estates handle probate timelines and beneficiary communication more effectively. |
What I’ve learned from watching inherited property sales go wrong
The most common mistake I see is executors treating an inherited property sale like a standard house sale. They skip the title check, assume probate is straightforward, and list the property before the legal groundwork is done. That approach creates problems that take months to untangle.
The second mistake is underestimating beneficiary conflict. When multiple people inherit a share of a property, they rarely agree on price, timing, or presentation. An executor who communicates clearly and early, sharing the valuation, the agent’s appraisal, and the proposed timeline, avoids most of these disputes before they start.
The third thing I’d flag is the 12-month wait before distribution. Many executors feel pressure from beneficiaries to release funds quickly. Resisting that pressure is the right call. A Family Protection Act claim filed after you have already distributed the estate puts your personal assets at risk, not just the estate’s.
The good news is that the process is manageable when you follow the steps in order. Get the title, apply for probate, open the estate account, get a valuation, and then list. Each step builds on the last. Rushing any one of them creates the delays people are trying to avoid.
— Aaron
Selling an inherited property? Easysale can help
Inherited property sales involve more moving parts than a standard sale, and the legal requirements in New Zealand are specific. Easysale works with executors and beneficiaries across New Zealand to make the process straightforward.
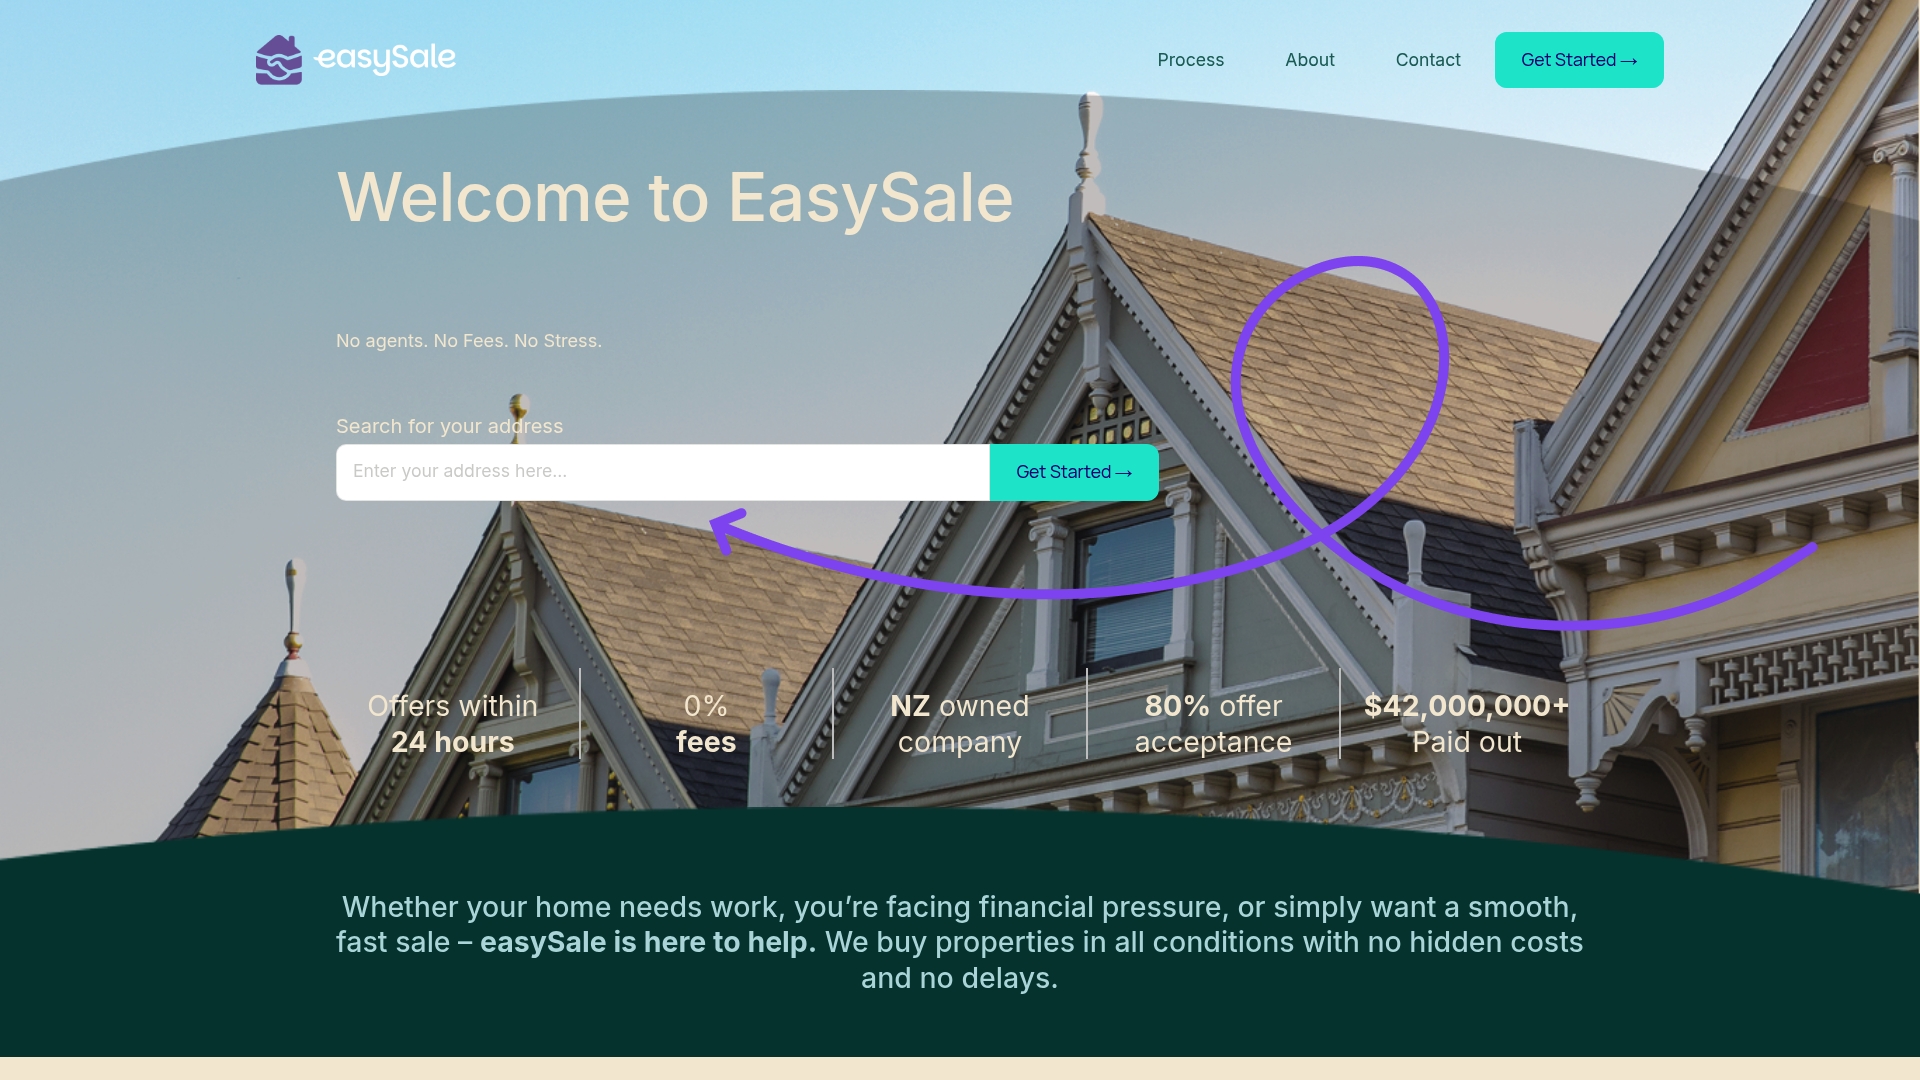
Easysale buys properties in any condition, with no agent commissions and no open homes. You submit your property details online, receive a no-obligation cash offer, and settle on a timeline that works for the estate. For executors managing probate timelines and beneficiary expectations, that kind of flexibility matters. Visit Easysale to get a cash offer and take the next step toward settling the estate.
FAQ
Do I need probate to sell an inherited property in New Zealand?
Probate is required when the deceased held property solely in their name or when estate assets exceed $40,000. Without a probate grant, you cannot legally transfer or settle the sale.
Can I list the property before probate is granted?
Yes. You can list and enter a conditional sale agreement before probate is issued, but settlement cannot proceed until the grant is in hand. Include a probate condition clause in the agreement.
Is there capital gains tax on an inherited property in New Zealand?
The bright-line test does not apply at the point of inheritance. Rollover relief means the transfer does not trigger immediate tax, but the original owner’s cost base and bright-line period carry over to the beneficiary.
How long does the inherited property sale process take?
The timeline depends on probate. A compliant probate application processes in 1–2 weeks, but the full grant typically takes 4–12 weeks. Add preparation, marketing, and settlement time, and most estate sales complete within three to six months.
What happens if beneficiaries disagree on selling the property?
Executors have the legal authority to sell estate property to settle debts and distribute the estate. Clear communication and a written record of all decisions help manage disagreements. If conflict escalates, a solicitor or mediator can assist.
Recommended
