
What is a fair offer? a guide for NZ homeowners in 2026
Most homeowners believe cash offers should match their home’s market value, but this assumption often leads to disappointment and confusion. Understanding what constitutes a fair cash offer is essential when you need to sell quickly in New Zealand’s property market. This guide clarifies the trade-offs between speed, convenience, and price, helping you make informed decisions about fast home sales without unrealistic expectations.
Table of Contents
- Why Cash Offers Are Often Lower Than Market Value
- How Cash Buyers Simplify And Speed Up The Sale Process
- Evaluating What Makes A Fair Offer For Your Home
- Practical Steps To Accept Or Negotiate A Fair Cash Offer
- Find Fair Cash Offers With Easy Sale NZ
- FAQ
Key takeaways
| Point | Details |
|---|---|
| Cash offers typically sit below market value | Speed and convenience justify the price difference for urgent sellers |
| Understanding trade-offs manages expectations | Fair offers balance quick completion with reasonable pricing |
| Cash buyers eliminate traditional sale risks | No financing fall-throughs, inspections, or lengthy negotiations |
| Company reputation matters as much as price | Transparent terms and proven track records indicate trustworthy buyers |
| Evaluating multiple factors ensures fairness | Consider timeline, conditions, and total costs saved |
Why cash offers are often lower than market value
Cash offers typically result in lower sale prices than market value due to the convenience and speed they provide. This pricing difference isn’t arbitrary but reflects genuine value that cash buyers deliver to sellers facing urgent circumstances.
When you sell through traditional methods, you bear multiple costs that cash buyers absorb. Estate agent fees alone consume 2-4% of your sale price, while marketing expenses, professional photography, and open home costs add thousands more. Cash buyers eliminate these expenses entirely, allowing them to offer lower prices whilst still providing net value to sellers.
The role of cash buyers in NZ property sales centres on removing uncertainty from transactions. Traditional sales often collapse when:
- Buyers’ mortgage applications get declined after weeks of processing
- Building inspections reveal issues that renegotiate or cancel deals
- Market conditions shift, causing buyers to withdraw offers
- Chain sales fall through, leaving you back at square one
Cash transactions sidestep all these risks. You receive certainty from day one, which carries enormous value when facing foreclosure, relationship breakdowns, or urgent relocations. The lower offer compensates buyers for providing guaranteed completion without contingencies that plague conventional sales.
“The peace of mind knowing the sale will definitely complete is worth more to me than holding out for a higher price that might never materialise,” explains one Auckland seller who avoided foreclosure through a cash sale.
Pro Tip: Calculate your true net proceeds from a traditional sale versus a cash offer. Factor in agent fees, marketing costs, potential repair expenses, and holding costs during a lengthy listing period. The cash offer often delivers similar or better net results with far less stress.
How cash buyers simplify and speed up the sale process
Traditional property sales in New Zealand typically require 60-90 days from listing to settlement, assuming everything proceeds smoothly. Cash offers expedite the selling process, potentially closing in as little as a week, which provides critical advantages for sellers facing time-sensitive situations.
The conventional sale timeline includes multiple bottlenecks that cash transactions eliminate entirely. Mortgage underwriting alone consumes 30-45 days, during which banks scrutinise buyer finances, order valuations, and assess lending risks. Cash buyers skip this entire phase because they purchase with available funds, not borrowed money.
The cash home buying NZ process follows a streamlined path:
- Submit your property details through a simple online form or phone call
- Receive an initial offer within 24-48 hours based on current condition
- Accept the offer and choose your preferred settlement date
- Complete legal paperwork with minimal requirements
- Settle and receive funds, often within 7-14 days
This efficiency stems from removing conditional clauses that complicate traditional contracts. Cash buyers typically purchase properties “as is, where is,” meaning you avoid costly pre-sale repairs, renovations, or even basic cleaning. You also skip the emotional toll of staging your home, hosting repeated viewings, and maintaining show-ready presentation for weeks or months.
Settlement flexibility represents another significant advantage. Traditional buyers often need specific timing to align with their own property sales or mortgage approvals. Cash buyers accommodate your schedule, whether you need immediate completion or prefer a delayed settlement that allows time to relocate.
Pro Tip: Before accepting any cash offer, request proof of funds or financial capacity. Legitimate cash buyers readily provide bank statements or letters from their financial institutions demonstrating their ability to complete the purchase without financing contingencies.
Evaluating what makes a fair offer for your home
Determining fairness requires looking beyond the dollar figure to assess total value delivered. Homeowners should manage their expectations when considering a cash offer, understanding that it may not equal the full market value but provides compensating benefits.
Start by researching your property’s realistic market value through recent comparable sales in your area. Online property platforms show recent sales data, though remember these reflect traditional sale prices before deducting agent fees and other costs. A fair cash offer typically ranges from 70-85% of market value, depending on property condition, location, and current market dynamics.
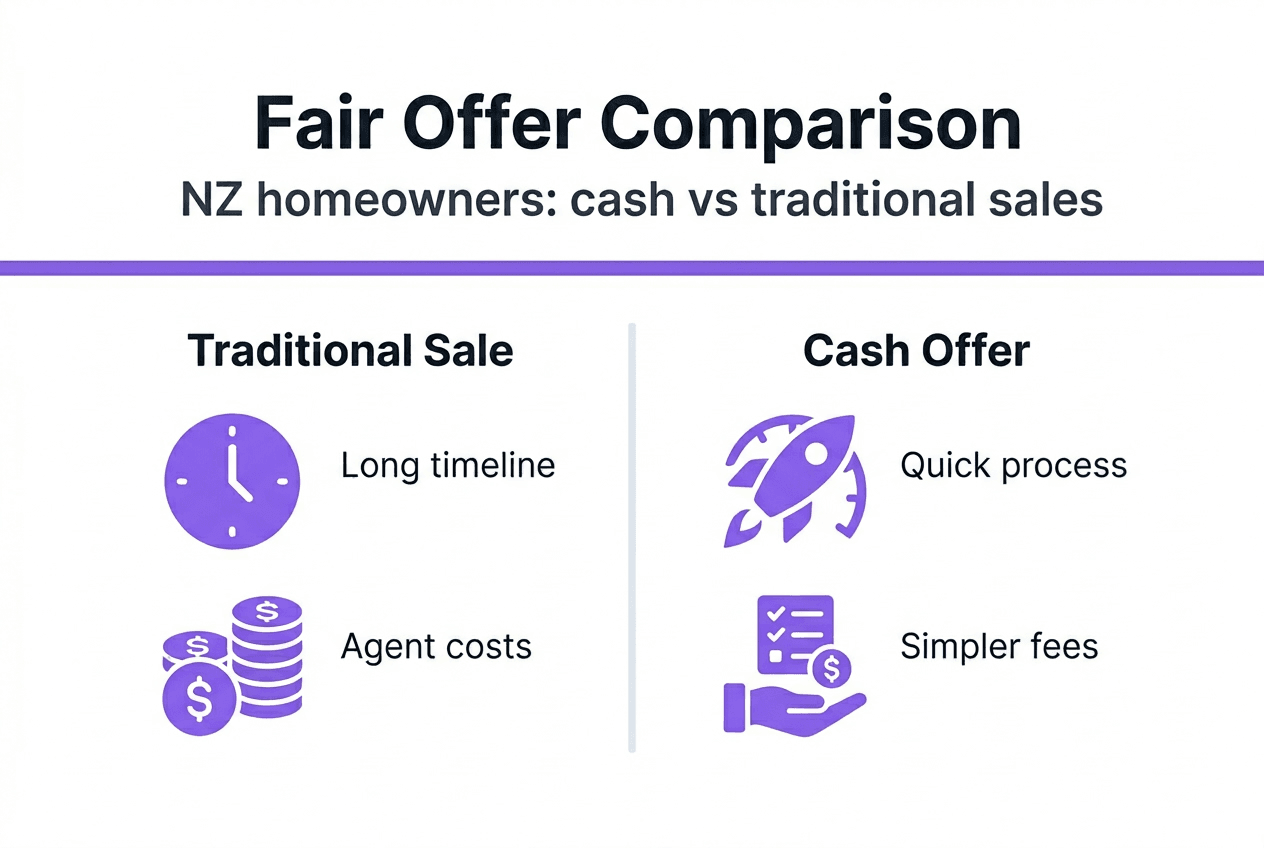
The speed differential between sale methods carries quantifiable value that many sellers overlook. Consider this comparison:
| Factor | Traditional Sale | Cash Sale |
|---|---|---|
| Timeline to completion | 60-90 days | 7-14 days |
| Agent commission | 2-4% of sale price | None |
| Marketing costs | $2,000-$5,000 | None |
| Pre-sale repairs | Often required | Not needed |
| Fall-through risk | 20-30% | Near zero |
| Holding costs during sale | Rates, insurance, mortgage payments | Minimal due to speed |
Buyer reputation deserves equal weight with price when evaluating offers. Research the company’s track record through online reviews, testimonials, and industry associations. Established cash buyers operate transparently, clearly explaining their offer calculations and showing proven completion rates.
Transparency in fees and conditions separates legitimate buyers from problematic operators. Fair offers include straightforward documentation showing exactly what you’ll receive at settlement, with no hidden deductions or surprise costs emerging later. Why sell your house for cash in NZ becomes clearer when you understand these transparency standards.
Your personal circumstances significantly influence what constitutes a fair offer for your situation. Facing foreclosure, urgent relocation, or inherited property complications makes speed and certainty more valuable than maximising sale price through lengthy traditional marketing.
Quick home sales through cash buyers in NZ suit specific scenarios where conventional selling creates more problems than it solves. Property requiring extensive repairs, difficult-to-sell locations, or complex ownership situations often benefit most from cash transactions.
Pro Tip: Request a detailed breakdown showing how the buyer calculated their offer. Reputable cash buyers explain their pricing methodology, including comparable sales data, condition adjustments, and their required margin for assuming purchase risks and providing immediate certainty.
Practical steps to accept or negotiate a fair cash offer
Cash home buying companies purchase houses directly from homeowners, bypassing the traditional real estate market. Once you receive an offer, following systematic steps ensures you protect your interests whilst moving towards successful completion.
Verifying buyer credentials forms your essential first step. Request company registration details, check their business history, and search for reviews from previous sellers. Established cash buyers willingly provide references or testimonials demonstrating their track record of completed purchases.
Review all offer documents thoroughly before signing anything. Key elements to examine include:
- The exact purchase price and settlement date
- Any conditions or contingencies attached to the offer
- Who pays for legal fees, council rates, and other settlement costs
- Deposit amounts and how they’re held
- Your rights if the buyer fails to complete
Negotiation remains possible even with cash offers. Common negotiation points include:
- Settlement timing that better suits your circumstances
- Including or excluding certain fixtures, fittings, or chattels
- Slight price adjustments based on recent comparable sales
- Flexibility around property access for buyer inspections
Many cash buyers purchase properties as-is, which saves you substantial repair costs and preparation time. This approach particularly benefits sellers with properties needing significant work, as renovation expenses often exceed the value they add in traditional sales.
Follow these numbered steps when responding to cash offers:
- Obtain at least two or three cash offers to establish competitive pricing
- Compare total net proceeds after accounting for all costs and timelines
- Verify each buyer’s credentials and review their standard contract terms
- Negotiate any terms that don’t suit your circumstances
- Engage a solicitor to review contracts before signing
- Prepare necessary documentation including property titles and rates certificates
- Maintain communication throughout the settlement period
Navigating NZ property sales becomes significantly simpler with experienced legal representation. Whilst cash sales involve less complexity than traditional transactions, having a solicitor review contracts protects you from unfavourable terms or unexpected obligations.
Understand your seller rights throughout the process. You can withdraw from negotiations before signing a binding agreement, you’re entitled to independent legal advice, and you should receive all promised payments on schedule. Reputable property cash buyers in NZ respect these rights and operate with complete transparency.
Preparing your paperwork in advance accelerates the settlement process. Gather your property title, recent rates notices, insurance documents, and any warranties for renovations or improvements. Having these ready when requested prevents delays that might postpone your settlement date.
Find fair cash offers with Easy Sale NZ
If you’re facing urgent circumstances requiring a fast, hassle-free property sale, Easy Sale NZ specialises in providing fair, transparent cash offers throughout New Zealand. We understand that speed and certainty matter as much as price when you’re dealing with challenging situations.

Our service particularly suits homeowners managing retirement downsizing and house sales in NZ, where simplified transactions reduce stress during major life transitions. We also buy damaged houses with fair cash offers, purchasing properties in any condition without requiring costly repairs or renovations. Easy Sale NZ delivers straightforward, no-obligation offers with settlement timing that suits your circumstances, providing the certainty and speed you need when traditional selling creates more problems than solutions.
FAQ
What is considered a fair offer when selling my home for cash?
A fair cash offer balances reasonable pricing with the genuine value of speed, certainty, and convenience. It typically ranges from 70-85% of market value, reflecting costs you avoid like agent fees, marketing expenses, and repair requirements. The offer should feel appropriate given your circumstances, timeline needs, and the buyer’s transparency about terms and calculations.
Why do cash buyers offer less than traditional buyers?
Cash buyers assume more risk by purchasing properties without financing contingencies, building inspections, or due diligence periods that protect traditional buyers. They pay immediately with available funds rather than borrowed money, eliminating mortgage approval delays and associated fall-through risks. This risk assumption, combined with costs they absorb for as-is purchases and rapid settlements, justifies their lower offering prices whilst still delivering net value to sellers.
How can I make sure the cash offer I get is fair?
Compare your offer against recent local sales data and obtain multiple cash offers to establish competitive pricing benchmarks. Research the buyer’s reputation through reviews, testimonials, and completion track records. Verify they provide transparent breakdowns of their offer calculations and clear documentation of all terms. Understanding why you should sell your house for cash in NZ helps you evaluate whether the trade-offs suit your specific circumstances and timeline requirements.
What are the risks of accepting a very low cash offer?
Accepting an offer significantly below fair market range means losing substantial equity in your property that you might never recover. Extremely low offers sometimes indicate inexperienced or unethical buyers who may not complete the purchase or might impose unexpected conditions later. Ensure your urgent circumstances genuinely justify accepting a low offer rather than exploring slightly longer-timeline alternatives that preserve more equity whilst still meeting your needs.
Recommended
